
Canadian canola strengthens its position in the EU market amid declining supplies from Ukraine
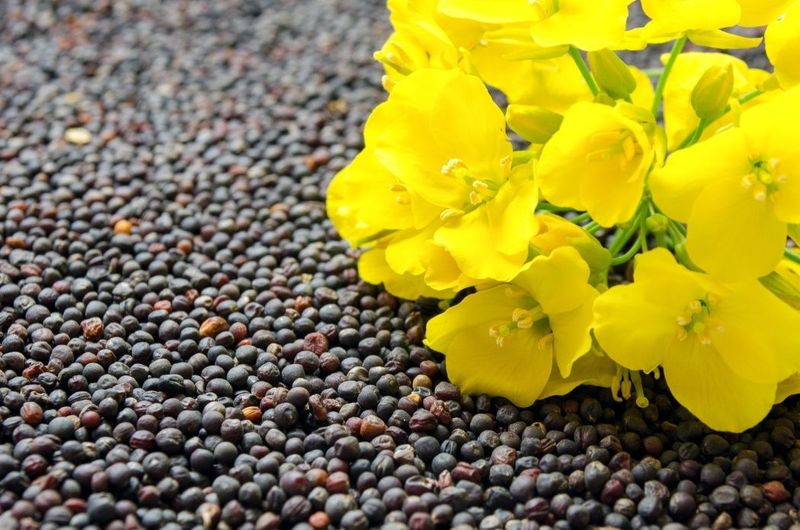
Canada has significantly increased its canola exports to the European Union, benefiting from reduced Ukrainian rapeseed shipments due to logistics restrictions. According to Agrarmarkt Informations-Gesellschaft (AMI), the EU imported 121.7 thsd tons of Canadian canola in July–September 2026, compared with virtually no shipments during the same period last year. This made Canada the third-largest rapeseed supplier to the European market. However, the high share of GM varieties in Canadian production restricts the use of this feedstock in certain segments of the EU market.
Overall, during the first three months of the MY 2026/27, EU rapeseed imports declined by 14% year-on-year to 871.5 thsd tons. Ukraine remained the largest supplier, although its exports to the EU fell by almost 44%, from 599.9 thsd tons to 336 thsd tons. The main reason was disruption to Black Sea shipping, which has constrained Ukrainian exporters. Under these conditions, alternative supply routes, particularly rail transportation, are becoming increasingly important.
Australia remains the EU’s second-largest rapeseed supplier, increasing shipments by 35% to 185.1 thsd tons and accounting for approximately 21% of total imports. However, a significant increase in sea freight costs from Australia is weakening the competitiveness of its products. According to the German Union for the Promotion of Oil and Protein Crops (UFOP), the trade dispute between Canada and China is also encouraging European buyers to shift toward Canadian canola, as Canadian exporters seek alternative markets.
Despite rising shipments, the use of Canadian canola in Europe faces certain restrictions due to the prevalence of genetically modified varieties. According to UFOP, the biofuel industry is the most important market for oil produced from Canadian canola. However, supplies to this sector must comply with European requirements for production sustainability, feedstock traceability and certification. This is forcing Canadian producers to increasingly adapt to EU regulatory standards.
Canada is therefore gradually strengthening its position in the European rapeseed market, primarily as a supplier of feedstock for biofuel production. However, the characteristics of Canadian canola and EU requirements governing its use limit its ability to fully replace Ukrainian supplies. For Ukraine, which remains the leading rapeseed supplier to the EU, restoring stable export logistics will be a key factor in maintaining its competitive position. Further trade developments will depend on the availability of Ukrainian rapeseed, international transportation costs and Canadian exporters’ ability to meet European market requirements.
Read also
Corn yields in France fall to 6.3 t/ha in 2026
Monthly report «VegOil Market Risk Navigator for Ukraine», September 2026
Ahlers – Logistics Partner of 4S BUSINESS SUMMIT
IGC raises global corn production forecast but expects grain stocks to decline
Brazil’s soybean acreage expansion to slow to a 20-year low — Conab
Got additional questions?
We will be happy to assist!
Write to us
Our manager will contact you soon