
Ukraine’s grain surplus: Why a strong harvest could squeeze farm margins
Market overview
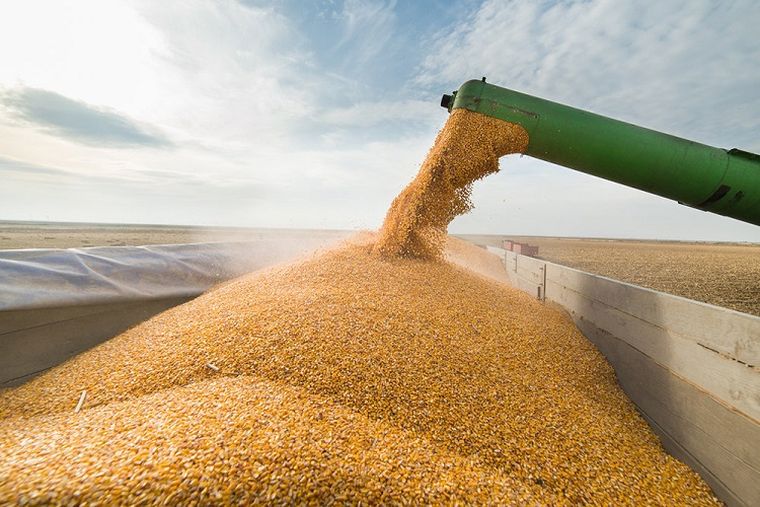
Ukraine’s grain market is entering a season marked by a widening gap between production capacity and the ability to market the crop. Improved yields are supporting wheat supply, while corn retains strong production potential. Yet the longer-term trajectories of output and exports are diverging: higher harvest volumes are not translating into proportionate overseas shipments. UkrAgroConsult estimates total grain production in MY 2026/27 at 65.6 mln tons..
Export logistics, rather than grain availability alone, are becoming the main determinant of market performance. Shipment projections now reflect the practical capacity of maritime, Danube and western land routes instead of theoretical export potential. As a result, even favorable crop outcomes may coincide with lower exports; the divergence between production and shipments is particularly pronounced for corn. The next phase will depend on the reliability and availability of export corridors.
Domestic stock accumulation is turning storage infrastructure into a critical element of market balance. Following fluctuations in earlier seasons, the combined opening-stock trajectory for wheat and corn points to a sharp build-up at the beginning of MY 2027/28, potentially approaching 31 mln tons. However, balance-sheet volumes should not be confused with commercially usable grain: limited storage and drying capacity, high moisture and delayed harvesting expose the crop to physical losses and quality deterioration.
Corn adds a distinct layer of seasonal uncertainty. Promising early yields coexist with the prospect that some fields will remain unharvested until spring, leaving recoverable volumes and quality exposed to winter conditions. An upward revision to industrial processing offers some support for domestic demand but does not resolve the broader imbalance between supply and marketing capacity. Harvest timing, moisture management, storage conditions and proximity to buyers are therefore becoming more important commercial variables.
Price outcomes will largely depend on the logistics scenario. Prolonged restrictions would keep domestic prices under pressure, while storage, drying, financing and quality-control costs erode farm margins, especially in regions far from active export routes. A reopening of Greater Odesa ports could strengthen competition for Ukrainian grain and support farmgate prices, although a rapid release of accumulated stocks could weigh on Black Sea and global quotations. UkrAgroConsult emphasizes that the decisive question is not only how much grain can be exported, but how much can be preserved in marketable condition.
Key trends
- Expanding production under constrained logistics is widening the gap between potential grain output and volumes that can reach international buyers.
- Actual export corridor capacity is increasingly shaping grain balances as maritime, Danube and overland routes determine achievable shipments.
- Rapidly rising carryover stocks are increasing the importance of storage and drying capacity, while reported inventories may overstate marketable supply.
- Corn faces additional seasonal exposure from delayed harvesting, winter-related field losses and potential deterioration in grain quality.
- Domestic prices and farm profitability are becoming more sensitive to location, grain-holding costs and the timing of any port-export recovery.
Would you like to receive the full analytical report with all insights and data? Please complete the form to gain access to the material. The full version will be sent to your email.
Full version of the article is available to subscribers ‘BLACK SEA & DANUBE GRAIN REPORT’ and ‘BLACK SEA & DANUBE OILSEED REPORT’. You may request a sample report and apply for subscription. Be confident with your business strategy based on professional analysis and forecasts of the Black Sea & Danube agri market!
Read also
Sunflower oil export delays threaten corn storage capacity in Ukraine
Egypt, Turkey and Bangladesh seek alternatives to Black Sea wheat
Unexpected USDA report triggers record CME corn futures trading
4S Business Summit Rotterdam – Agenda Updated!
US beef exports rise 4%, while pork shipments fall 6%
Got additional questions?
We will be happy to assist!
Write to us
Our manager will contact you soon