
Kazakhstan expands linseed area by 41%, but production to remain unchanged year-on-year
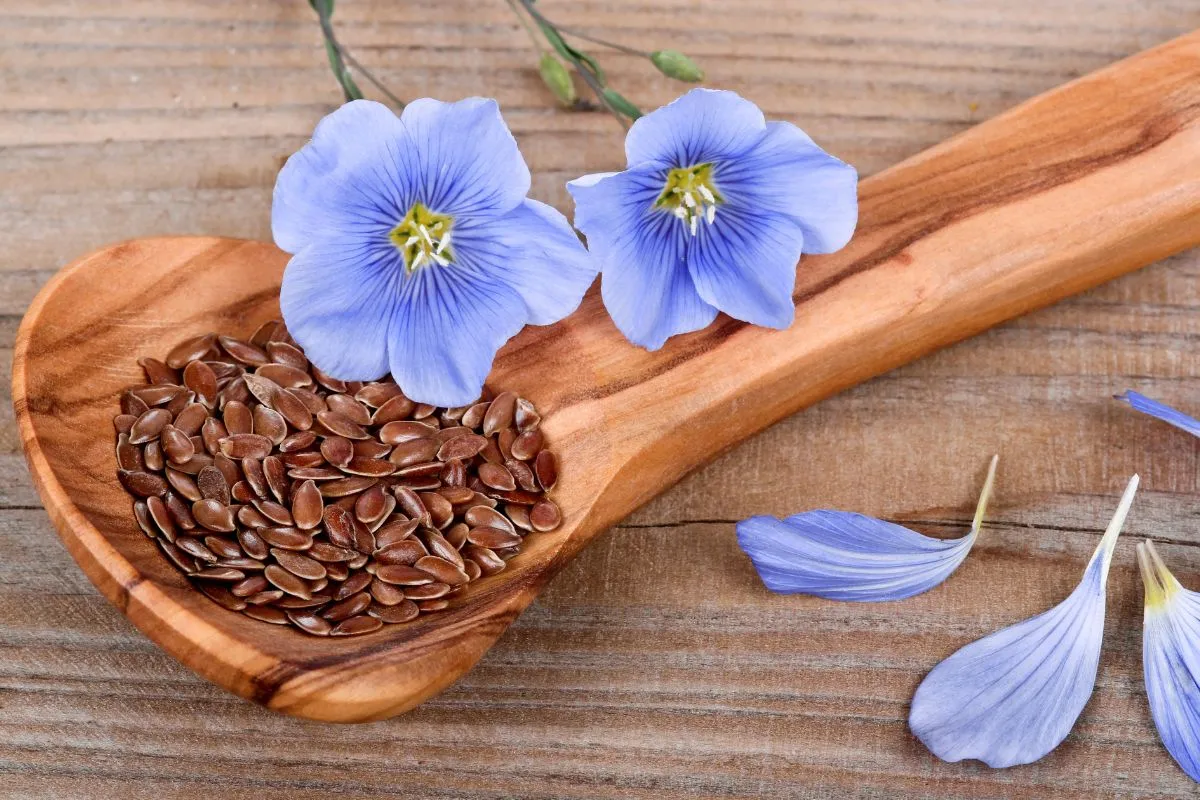
Kazakhstan’s linseed production is expected to reach 1.35 mln tons in 2026, matching the previous season’s level. According to the Grain Union of Kazakhstan, a significant expansion in planted area has failed to increase overall production due to summer drought and lower yields. This year, the area planted with linseed increased by 41.3% to 1.9 mln ha, but unfavorable weather conditions offset the benefits of expanded sowings.
Despite stagnant production, Kazakhstan has significantly increased its linseed exports. In September 2026, shipments reached 100.9 thsd tons, up 33% from August and 1.62 times the volume recorded in September last year. China remained the largest buyer, accounting for 71% of total exports, or 71.8 thsd tons. Shipments to China increased 2.7 times year-on-year, highlighting the growing importance of the Chinese market for Kazakh exporters.
Meanwhile, Kazakhstan increased linseed shipments to Afghanistan, Uzbekistan, Tajikistan and Pakistan. In contrast, exports to European destinations declined considerably. Shipments to Belgium fell 5.5 times, those to Poland decreased 1.8 times, while exports to Germany dropped threefold. This trend indicates a shift in export flows toward Asian markets amid increasing logistical difficulties in reaching Europe.
Rail transit restrictions through Russia and congestion at port facilities remain among the main obstacles to Kazakhstan’s exports. According to Yevgeny Karabanov, head of the analytical committee at the Grain Union of Kazakhstan, all applications submitted by Kazakh exporters for transit via the northwestern section of Russia’s railway network were rejected in October. This significantly complicates access to European buyers, and no improvement is currently expected during November or December.
Against the backdrop of logistical restrictions, prices for Kazakh linseed in European markets have been rising in recent months. Declining shipments to the EU, combined with stable overall production and stronger demand from China, could further reshape Kazakhstan’s export geography. For Kazakh producers and traders, key factors will include the availability of transit routes, transportation costs and opportunities to expand shipments to Asian markets.
Read also
Russian analysts do not expect Black Sea shipping to normalize before spring 2027
Ukraine cannot afford to buy up surplus grain from farmers
Sunseed prices in Ukraine decline as crushing plants shut down following Russian a...
Canada’s wheat production could decline by 10% but remain among the highest ...
Russia’s share of global sunflower oil exports could fall from 38% to 25%
Got additional questions?
We will be happy to assist!
Write to us
Our manager will contact you soon