
EU fertilizer prices remain high amid costly gas and raw material supply disruptions
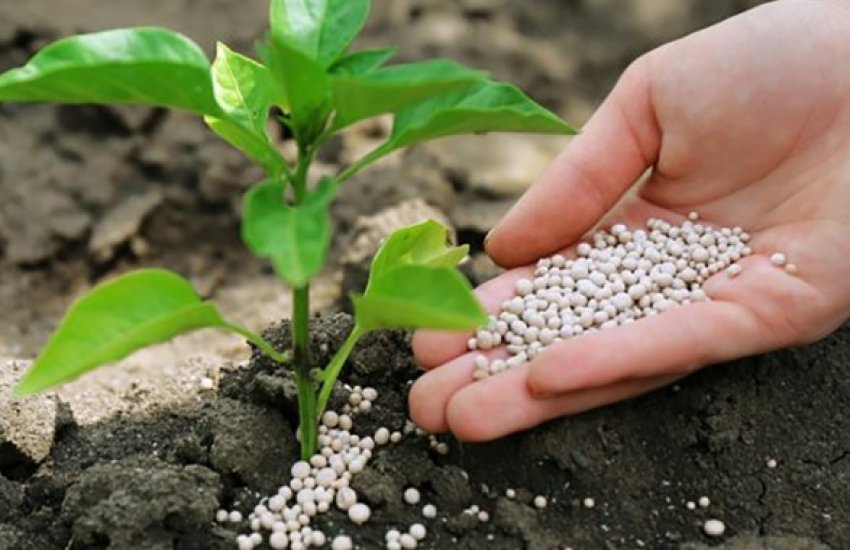
The European mineral fertilizer market continues to face pressure from high production costs, logistical constraints and risks of raw material supply disruptions in early November 2026. Nitrogen and phosphate fertilizers have been particularly affected, with prices remaining high despite subdued demand from farmers. Elevated natural gas prices, which are critical for nitrogen fertilizer production, and instability in international supply chains are adding further pressure to the market.
In France, urea was priced at €637/t as of November 2, while diammonium phosphate (DAP) cost €957/t and muriate of potash (MOP) €372.25/t. In Germany, urea prices on November 3 ranged from €605 to €745/t depending on the region, while urea ammonium nitrate solution (UAN) was quoted at €425–495/t. European nitrogen fertilizer producers continue to face the impact of high natural gas prices, while additional logistical difficulties complicate efforts to secure sufficient supplies for the market.
The phosphate fertilizer market is causing particular concern, as production depends heavily on the availability of sulfur and other raw materials. Shipping disruptions through the Strait of Hormuz are increasing the risk of shortages, while sulfur prices have exceeded $1,000/t, according to the cited market estimates. High raw material costs are already affecting phosphate fertilizer producers. In particular, Mosaic has suspended operations at some production facilities, while market participants warn that price pressure could persist until spring 2027.
Fertilizer prices also remain high in Poland. In late October and early November, urea was offered at approximately PLN 2,638–3,211/t excluding VAT across different regions of the country, while ammonium nitrate was priced at PLN 2,116–2,392/t. Against this backdrop, Polish authorities are considering importing up to 100 thsd tons of urea from Egypt to meet domestic market needs. Egyptian urea is expected to cost around PLN 2,280/t, compared with PLN 2,900–3,200/t for Polish-produced urea, raising concerns among domestic manufacturers about intensifying price competition.
Further developments in the European fertilizer market will largely depend on energy prices, raw material availability and international demand. Limited supplies from certain exporting countries and the possibility of another major urea procurement tender by India are creating additional uncertainty. At the same time, weak purchasing activity among European farmers is restraining further price increases in some market segments. Nevertheless, high production costs and supply disruption risks could keep EU fertilizer prices elevated ahead of the spring 2027 planting season.
Read also
Poland’s potato imports fall nearly 41% in volume and 46% in value
Canada’s canola crushing capacity expands to 15 mln tons per year
Whole wheat flour accounts for just 4.1% of total US flour production
Solar panels on pastures reduce heat stress in dairy cows and improve forage quali...
Netherlands onion harvest falls 15% due to drought and reduced planting area
Got additional questions?
We will be happy to assist!
Write to us
Our manager will contact you soon